Nuclear Energy’s Comeback: How AI’s Power Hunger Is Rewriting the Energy Playbook
The explosive growth of AI data centers is driving a surge in electricity demand, reviving interest in nuclear power as a reliable, low-carbon energy source for the AI era.
Table of Contents
Nuclear energy is back. Not because the science changed. Not because the politics suddenly got easier. Because AI got hungry — and nothing else on the grid can feed it at scale. In September 2024, Microsoft agreed to buy power from Three Mile Island.
Yeah. That Three Mile Island.
Unit 2 of that plant had a partial core melt in 1979 — the worst nuclear accident in U.S. history — and the name has been American shorthand for “nuclear disaster” ever since. I think most people, if you’d asked them a few years ago, would’ve said the idea of a major tech firm signing a 20-year deal to restart it was… not serious. Not a real thing that would happen.
And yet. Here we are.
Now, I want to be upfront: nuclear energy never fully died. That’s a simplification people reach for, and I’ve used it myself, but it’s not quite right.
U.S. reactors were still producing roughly 19% of the country’s power when this deal dropped. Vogtle Unit 3 in Georgia came online in 2023. France, South Korea, China — none of them ever really stopped building.
But in the U.S.? The economics were a mess. Plant after plant shut down early — not for safety reasons, but because they couldn’t win a price war against cheap gas. Three Mile Island Unit 1 went dark in 2019 for that exact reason. So when I say AI “brought nuclear back from the dead,” what I mean is: it changed the math fast enough that plants already losing money suddenly had a buyer willing to sign a 20-year contract for every watt they could produce.
That buyer was Microsoft. One of the most valuable companies on earth. Twenty years. All of it.
Here’s the part worth being precise about, though: “all of it” describes a contractual procurement arrangement, not a dedicated wire. Microsoft’s PPA is a commercial agreement to purchase the plant’s output — the electrons enter the interconnected PJM grid, the same regional pool everyone else in the Mid-Atlantic draws from, and Microsoft doesn’t receive physically identifiable electrons traceable back to this specific reactor. There’s no dedicated line running from the reactor to a Microsoft data center. The contract associates Microsoft’s procurement with the plant’s 835 MW of generation and its clean-energy attributes, matched against what its data centers pull from the grid elsewhere in PJM territory. Same structure applies to nearly every corporate nuclear deal in this piece — Google, Amazon, Meta. Generation and consumption happen in the same regional grid, not through a private cable.
As for the restart itself, worth keeping the stages straight instead of one headline date: signing a PPA isn’t the same as restoring a license, which isn’t the same as loading fuel, which isn’t the same as commercial operation. As of mid-2026, the NRC and Constellation have targeted an operating license decision around May 2027, with commercial operation sometime after — Constellation hasn’t committed to a firm grid-connection date beyond “before 2031, ideally sooner.” A June 2026 FERC waiver helped clear an interconnection bottleneck, per Power Engineering. Don’t mark your calendar in pen, but the paperwork is genuinely moving.
The Hunger Is Real — And It’s Growing Fast
Okay, before I get into the nuclear stuff — I need to talk about the actual scale of what AI eats. And I’ll be honest: I was looking over this data earlier while putting the piece together, and the numbers are genuinely hard to sit with. I kept rechecking them because they felt too extreme.
I know what you’re thinking. You’ve heard the “AI uses a lot of power” line. You’ve probably glazed over it. I did too, for a while.
The International Energy Agency’s Energy and AI report (April 2025) says data centers globally used about 415 terawatt-hours (TWh) of electricity in 2024. That’s roughly 1.5% of all power used worldwide. Fine, not wild on its own. But here’s where it gets weird — in 2025 alone, electricity demand from AI-focused data centers jumped 50%, per the IEA’s Key Questions on Energy and AI update (April 2026). Data centers overall grew 17%. Total global electricity demand? Three percent.
Three. Percent.
Look, I know those numbers sound dry. Bear with me here, because the gap matters. The IEA projects the whole data center sector will roughly double its electricity use — from 415 TWh to around 945 TWh — by 2030. That is the equivalent of bolting Japan’s entire current power demand onto the existing global grid. Just for data centers. In six years.
By the way — these figures cover all data center workloads, not just AI. AI training, AI inference (every query you send), regular cloud, enterprise computing, storage. Everything. AI is the fastest-growing piece and the main driver of new investment, but it’s not the only load in the building. The IEA is careful about this. So am I.
So why is AI specifically so hungry? Let me jump to the thing that actually surprised me most when I dug in:
Inference is the real bill. Not training. Every time you prompt a model, it chews through billions of parameters. Every. Single. Time.
Multiply that by hundreds of millions of daily users, and the energy math gets genuinely brutal. Training happens once per model. Inference runs continuously, forever.
Multiple analyses suggest inference ends up exceeding training energy over a model’s whole life — though honestly the exact split varies a lot depending on deployment scale, model size, whether teams are using quantization, what hardware generation they’re on. I find that most coverage gets this completely backward and focuses on the training number because it’s dramatic. Training is the event. Inference is the electricity bill you pay every month until the model is retired.
On training: independent researchers have put GPT-4’s energy use in the tens-of-gigawatt-hour range — figures around 50 GWh show up in third-party work from RISE Research Institutes of Sweden and academic papers drawing on leaked hardware config data. OpenAI has never released an official number. Methodology assumptions vary. Rough direction, not a hard fact.
Now here’s the part I want to rant about for a second, because I don’t think it gets nearly enough attention — cooling. I work in PCB manufacturing and AI rack infrastructure, and the thermal problem at the board level is frankly just a total mess to deal with right now.
Everyone talks about the grid. Nobody talks about the fact that NVIDIA Blackwell-generation accelerators approach or exceed 1 kW per GPU in some rack configurations, which means traditional air cooling is already hitting a wall. Direct-to-chip liquid cooling, immersive cooling — these are becoming standard, and they also consume power.
So you get this situation where the chips get more efficient, the cooling systems get more power-hungry, and the net electricity bill barely moves. IPC-2152 current-carrying standards are being pushed in ways that simply weren’t on the table three years ago. It’s a solvable problem, but it’s not a solved one.
And it’s worth saying clearly: none of this is a steady, predictable load. AI accelerators don’t draw power like a toaster pulling a fixed current — they spike. A burst of inference requests can swing a GPU’s power draw dramatically in fractions of a second, and the voltage regulator modules (VRMs) feeding those chips have to react almost instantly, or you get voltage droop — the chip not getting power at the moment it needs it. That’s a rack-and-board-level engineering problem, and it exists no matter whether the electricity upstream comes from a nuclear plant, a gas turbine, or a wind farm. Steady baseload generation doesn’t automatically mean steady power at the chip.
Which gets at something easy to gloss over: a facility’s headline megawatt figure and its usable compute capacity aren’t the same number. A facility rated for 500 MW isn’t delivering 500 MW to GPUs — a real slice goes to cooling, conversion losses at each transformer and PSU stage, networking, and overhead baked into the facility’s Power Usage Effectiveness (PUE) ratio. Modern AI facilities target PUE around 1.2, which still means roughly 15–20% of total power isn’t going to compute. Generation capacity, facility capacity, and GPU wattage are three different numbers — conflating them is how a nuclear PPA looks like it solves more than it does.
Solar rests. Wind stops. AI data centers run at 3 AM in January. No flexibility there.
To be honest, when I first saw the IEA numbers, I thought they were too aggressive. Then 2025 happened and came in right on target.
Why Wind and Solar Can’t Do This Alone
Fair enough, but — I want to be clear I’m not anti-renewable before I say this. Solar and wind are real, important, and getting cheaper every year. Some of my closest clients are deep in that space. But there’s a hard physical wall that makes them insufficient on their own for AI-scale power, and I think people dance around it too much.
One word. Intermittency.
Sun doesn’t shine at night. Wind dies when it’s calm. AI data centers can’t run on “mostly available.” They need power at 3 AM, in a blizzard, in the middle of July, all of it, no gaps. Battery storage is moving fast — utility-scale costs have dropped a lot over the past decade — but at the continuous multi-hundred-megawatt baseload scale we’re actually talking about, storage just can’t close that gap yet. The technology is moving. The buildout is not keeping pace.
The IEA’s own projections make this uncomfortable. Renewables will cover nearly 50% of new data center electricity demand through 2030. Genuinely impressive. But natural gas and coal together are projected to cover over 40% of that same new demand. Tech companies have legally binding net-zero pledges. They can’t plug that 40% gap with gas without blowing up their sustainability numbers. They needed something that runs 24/7, doesn’t burn carbon, and actually exists at scale today.
For those reasons — and this is my own read of the current U.S. grid, not a law of physics — nuclear energy is, right now, the thing that fits all three constraints at the scale hyperscalers need. Geothermal or large hydro can do something similar in specific geographies; they’re just not available at the scale or locations most AI buildout is happening. So “only game in town” elsewhere in this piece means for U.S. AI infrastructure at current buildout speed — not the only clean baseload source on Earth.
Why Nuclear Energy, Specifically?
Three things. That’s it.
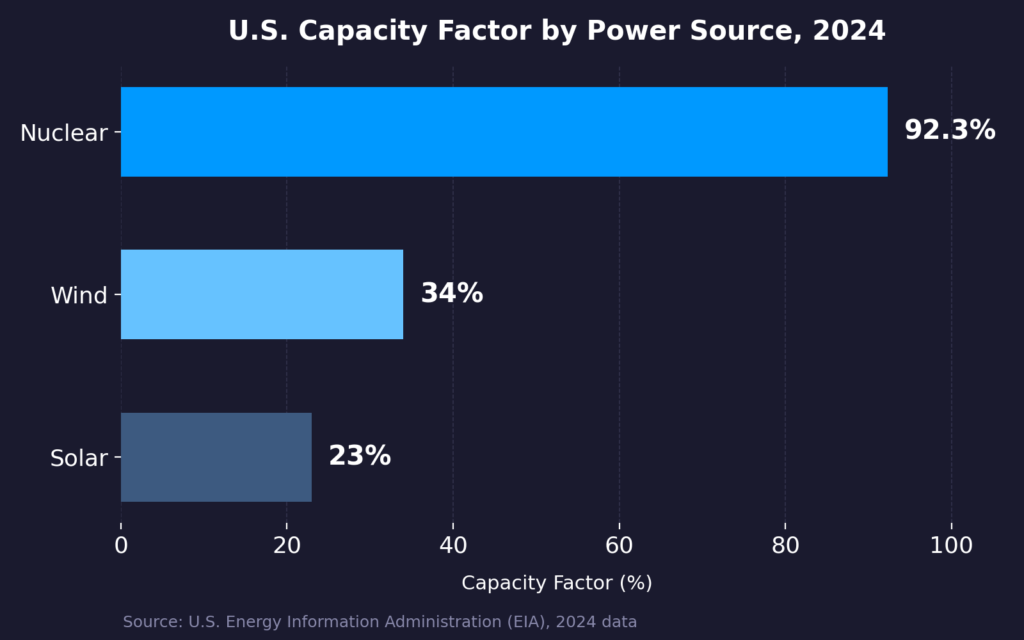
1. It runs. All the time. The U.S. nuclear fleet hit a 92.3% capacity factor in 2024, per EIA — highest of any power source in the country. Solar averages around 23%, wind around 34%. Three Mile Island Unit 1 specifically ran at 96.3% of max capacity in its last full year before the 2019 shutdown — Constellation’s own figures. Grid planners use fancier metrics like Effective Load Carrying Capability (ELCC) that account for storage and demand response, which is fair. Worth being clear what capacity factor actually proves, too: it measures how often a plant produces power relative to its maximum output — it says nothing about construction cost or project timeline. High capacity factor is necessary for reliable baseload; it isn’t proof nuclear is the cheapest or fastest option to build. But on the basic question of “is the power there when I need it,” nuclear just wins.
2. Low-carbon. Near-zero direct operational emissions — and yes, full lifecycle including construction and fuel processing is low but not zero, I cover this more in the Carbon section below because I think the “carbon-free” marketing is a bit sloppy. For companies with binding net-zero targets, though, operational emissions are what the scoreboard measures. A gas peaker doesn’t fix that. Nuclear energy does.
3. One plant. 835 MW. About 1.3 square miles. To get the same annual output from solar, you’d need 45–75 square miles, because solar capacity factors run 17–28% and you need 3–5x the installed capacity to match nuclear’s year-round output — that’s per Nuclear Energy Institute analysis. Wind is 260–360 square miles. I think the density case for nuclear is genuinely underrated in the public conversation.
On the other hand — maybe I’m wrong to keep framing this as nuclear versus renewables. At the end of the day, we probably need all of it running simultaneously. But for 24/7 carbon-free baseload at the scale AI actually demands, right now, nuclear energy is the strongest option on the table.
Big Tech Is All In. Not Just Microsoft.
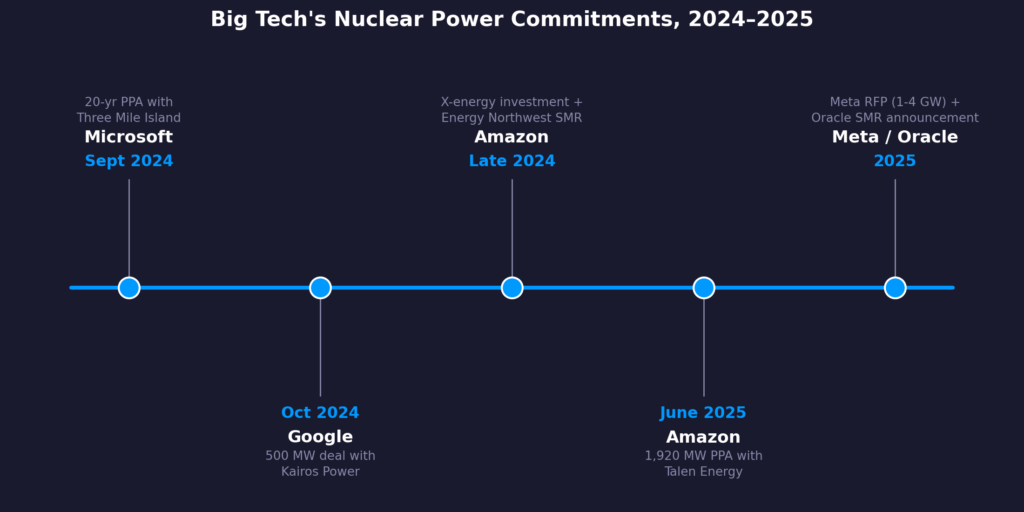
Three Mile Island was the loudest moment in this story. Not the only one.
Google signed a 500 MW deal with Kairos Power in October 2024 — first corporate SMR fleet agreement in U.S. history. Now here’s where it gets weird: most press coverage just calls these “molten salt reactors,” which is actually not quite right.
Kairos builds fluoride salt-cooled high-temperature reactors (KP-FHR) — solid TRISO pebble fuel, FLiBe molten salt coolant, operates at low pressure. Different architecture from a dissolved-fuel molten salt reactor, different safety profile, and the distinction matters if you’re actually evaluating the technology.
Worth separating two things most coverage flattens into one date: Kairos broke ground on its Hermes 2 demonstration plant in Oak Ridge in April 2026 — the first Gen IV, power-producing reactor design ever to get an NRC construction permit — with Kairos targeting potential initial power to the Tennessee Valley Authority grid, up to 50 MW, as early as late 2027, pending construction and testing, helping decarbonize Google’s data centers in Tennessee and Alabama. That’s a demonstration proving the technology at commercial scale for the first time. It is not yet Google’s dedicated 500 MW commercial fleet from the original October 2024 agreement — that fleet targets a first commercial unit around 2030, full seven-reactor build-out by 2035. Demonstration first, commercial fleet after. Google also put early-stage capital into Elementl Power in May 2025 for three more U.S. sites, at least 600 MW each, 1.8 GW combined — that’s development funding for site prep, not a signed PPA, and no reactor technology has been chosen yet.
Amazon went on what I can only describe as a nuclear shopping spree in late 2024. Co-investment in SMR developer X-energy’s $500M Series C, plus a 320 MW SMR project with Energy Northwest in Washington State.
Then in June 2025, they finalized a 17-year PPA with Talen Energy — up to 1,920 MW of nuclear power from Susquehanna through 2042, confirmed in Talen’s SEC Form 8-K. Talen’s own investor presentation projects roughly $18 billion in revenue over the contract life.
By the way — you’ll see the “$20 billion Amazon nuclear deal” in headlines everywhere. That’s actually Amazon’s separate Pennsylvania data center infrastructure investment announced the same week. Completely different commitment. Don’t let anyone conflate them.
Meta put out an RFP for 1 to 4 gigawatts of new nuclear. I think people underreact to that number. Four gigawatts. Multiple large plants. One company.
Oracle’s Larry Ellison dropped this on the Q1 FY2025 earnings call: they’re designing a gigawatt-scale data center powered by three SMRs, and stated the site has building permits. No location. No NRC licensing timeline — that takes years separately. Strong signal. Not a hard announcement. Announced is not the same as contracted, and contracted is not the same as licensed — worth remembering every time a new nuclear-for-AI headline lands.
Per the IEA’s April 2026 update, the pipeline of conditional offtake agreements between data centers and SMR projects went from 25 gigawatts at end-2024 to 45 gigawatts by April 2026. Eighteen months. That’s not a trend. That’s a structural change in how the technology industry thinks about where power comes from.
What Even Is an SMR? (I Keep Using This Term)
I realize I’ve been dropping “SMR” all over this piece without actually explaining it. Let me fix that.
Standard nuclear plants are enormous. We’re talking 1,000+ MW, tens of billions of dollars, and timelines that stretch 10–20 years just to get to first power — that’s before you count the permitting decades. Not workable for a company that needs power by 2030.
Small modular reactors are a genuinely different category. The output is smaller — typically somewhere in the 50–300 MW per module range rather than 1,000+ MW for a conventional plant. And the factory-built angle is real: most of the heavy component work happens in a controlled factory setting, then ships to the site for assembly. The theory is that this cuts both build time and cost significantly compared to traditional on-site construction.
I want to be honest here, though, because I think some of the SMR hype is running ahead of the evidence. No Western SMR program has actually demonstrated these cost reductions at full commercial scale yet.
First-of-a-kind projects carry premiums — that’s just how new industrial tech works until supply chains mature and you get the second, third, tenth build. Long-lead nuclear components such as large forgings and pressure vessels can become schedule constraints as demand for them scales — arguably a real ceiling on how fast these announced gigawatts show up on a grid, since a signed PPA doesn’t manufacture a reactor pressure vessel.
The promise is real. The receipts aren’t in. You can add capacity modularly as demand grows instead of committing to one massive upfront bet, and the design variety is genuinely interesting — pressurized water, high-temp gas, molten salt, fast neutron, each with different physics.
The IEA’s take is that AI money could accelerate SMR commercialization faster than the energy sector alone ever would have managed. I think that’s probably right. When Google and Amazon and Microsoft are anchor customers, the financing math for the entire industry changes.
The Nuclear Energy Carbon Argument (It’s Messier Than the Press Release Says)
Look, I want to be straight about this because I think the “carbon-free nuclear” messaging gets repeated without enough scrutiny.
Tech companies call these deals carbon-free. In terms of operational emissions — what the plant puts into the air while it’s running — that’s accurate. But building the plant in the first place has a real carbon cost. Steel, concrete, specialized manufacturing, transport — it adds up. Lifecycle emissions for nuclear are low compared to gas or coal by essentially any methodology, but they are not zero. Anyone who tells you otherwise is doing marketing. Good marketing, maybe, but still.
Also: the IEA is projecting natural gas and coal will still cover over 40% of new data center electricity demand through 2030. Even with all this nuclear and renewables investment. The transition is happening — I genuinely believe that — but it won’t look clean in the near-term numbers, and I think it’s worth being honest about that rather than pretending the 20-year contracts fix everything overnight.
My take — and I know some people will push back — is that nuclear energy is the best option available right now for reliable, low-carbon, always-on power at the scale AI actually needs. Imperfect beats nothing. Running everything on gas indefinitely is worse, and pretending today’s battery storage can fill the gap isn’t an honest position.
What This Actually Means For You
You’re probably not building a reactor. Don’t sweat it. But this shift touches more than the energy sector, and I think a few of the knock-on effects are underappreciated.
Your electricity bill will feel this eventually, especially if you run operations in data center-dense regions. Virginia’s “Data Center Alley” is the textbook example — Dominion Energy has projected regional power demand could jump 85% over the next 15 years. That pressure lands somewhere.
Here’s a wrinkle worth knowing: not all of the demand behind those projections is real yet, and grid operators are starting to say so. In Texas, ERCOT’s interconnection queue for large loads — mostly AI data centers — ballooned from roughly 48 GW in 2023 to more than 474 GW by September 2026, prompting the state to freeze new grid connections while it audits which projects are actually financed versus speculative. PJM, the grid serving the mid-Atlantic (including Crane), is facing a version of the same problem — a Wood Mackenzie analysis puts utilities in PJM’s footprint on pace for 55 GW of new large-load growth by 2030, but that same analysis, along with commentary in the underlying FERC docket, flags that a share of those requests reflects developers filing duplicate interconnection applications across multiple sites to hedge against transmission uncertainty — proposed load, not firm or energized load. The point isn’t that AI demand is fake — the IEA’s growth figures are real and measured after the fact. It’s that a signed PPA or interconnection request is a forecast, not a delivered megawatt.
The political environment is shifting in ways I honestly didn’t see coming even a couple years ago. A Pew survey from April–May 2025 found 59% of U.S. adults now favor more nuclear plants, up from 43% in 2020, with gains across both parties. Bisconti Research’s 2025 numbers put it at 70%+. The Trump administration signed four executive orders on nuclear energy expansion, and a nuclear energy tax incentive law passed in July 2025. I’ve been watching energy policy discussions for a long time, and the level of bipartisan momentum here is genuinely new.
Now here’s the angle I think most energy-AI coverage completely misses, and it’s the one I care most about given my background: cybersecurity. Concentrating AI workloads onto nuclear-adjacent grid infrastructure creates an attack surface that flat-out didn’t exist before.
As hyperscalers tie operations directly to power plants through PPAs and co-location deals, the IT/OT boundary — the line between data center management software and the energy management systems (EMS) running those plants — becomes a legitimate target. Nation-state actors are already probing U.S. energy infrastructure — this is documented in public advisories from CISA (Cybersecurity and Infrastructure Security Agency) and the Department of Energy, not speculation. To be precise about the real risk: this is about operational disruption and control-system access at the IT/OT boundary — not a scenario where an intrusion directly manipulates reactor safety systems, which sit behind their own separate, heavily regulated, largely air-gapped architecture. The realistic threat is disruption and data compromise, addressed through segmentation and defense-in-depth — not a hacker “turning off” a reactor core.
AI clusters, with their BMC/IPMI interfaces and software-defined networking stacks, sitting as direct grid neighbors to nuclear facilities raises the stakes in ways nobody is fully accounting for yet. This isn’t an argument against nuclear energy. It’s an argument for treating cybersecurity as a day-one requirement in these deals, not an afterthought that gets bolted on six months after the contracts are signed.
Every prompt you send, every image you generate, every doc you run through an AI tool — it draws from the grid. That grid is being reshaped right now by 20-year contracts between the biggest tech companies on earth and plants that were shuttered three years ago.
The cooling towers at Three Mile Island have meant one thing in American culture for 45 years. Once the current licensing process concludes — and if the timeline holds — they’ll mean something else entirely.
I think most people will find that either fascinating or deeply strange. Maybe both. I’m honestly not sure which reaction is more appropriate.
What I keep coming back to is this: the AI industry’s appetite for power got so big, so fast, that it’s changing things most people assumed were already settled. The future of nuclear energy. The shape of the grid. Contracts measured in decades. None of that was supposed to look like this five years ago. And five years from now, I suspect it’ll look different again.
Pay attention to the energy story. It’s the one hiding behind every AI headline you read.
About the Author
Imran Valiani | Sales Director, PCB Electronics Manufacturing
20+ years working with major Bay Area and global tech clients. Founder of Silicon to Software, where I write about the hardware layer — PCB fab, AI gear, autonomous systems, and cyber — the stuff most tech writers have never touched. Literally.
Follow: X @SiToSoftware | LinkedIn
For more analysis of compute, power, cooling, and infrastructure constraints, explore the AI Hardware & Data Centers Resource Hub.
This article was developed with AI assistance and edited, fact-checked, and reviewed by the author. See my full AI disclosure.
Sources
- International Energy Agency (IEA) — Energy and AI report, April 2025. Energy demand from AI. https://www.iea.org/reports/energy-and-ai/energy-demand-from-ai
- International Energy Agency (IEA) — Key Questions on Energy and AI, April 2026. Executive summary. https://www.iea.org/reports/key-questions-on-energy-and-ai/executive-summary
- International Energy Agency (IEA) — Energy supply for AI, 2025. https://www.iea.org/reports/energy-and-ai/energy-supply-for-ai
- Constellation Energy — Crane Clean Energy Center launch press release, September 20, 2024. https://investors.constellationenergy.com/news-releases/news-release-details/constellation-launch-crane-clean-energy-center-restoring-jobs/
- U.S. Nuclear Regulatory Commission — Christopher M. Crane Clean Energy Center licensing docket and restart inspection activity. https://www.nrc.gov/info-finder/reactors/ccec
- Power Engineering — “FERC waiver cuts years off Three Mile Island nuclear plant restart timeline,” June 4, 2026. https://www.power-eng.com/nuclear/ferc-waiver-cuts-years-off-three-mile-island-nuclear-plant-restart-timeline/
- WITF / StateImpact Pennsylvania — Three Mile Island restart NRC public hearing coverage, July 2026.
- U.S. Energy Information Administration (EIA) — Nuclear capacity factor data, 2024. https://www.eia.gov/nuclear/data.php
- American Nuclear Society (ANS) — U.S. nuclear capacity factors, 2020–2022 tracking. https://www.ans.org/news/2025-05-02/article-6967/us-nuclear-capacity-factors-stability-and-energy-dominance/
- Nuclear Energy Institute (NEI) — “Land Requirements for Carbon-Free Technologies,” updated 2022. https://www.nei.org/news/2022/nuclear-brings-more-electricity-with-less-land
- Kairos Power — Hermes 2 groundbreaking press release, April 17, 2026; KP-FHR technology documentation; Google partnership page. https://www.kairospower.com/updates/kairos-power-breaks-ground-on-hermes-2-demonstration-plant | https://www.kairospower.com/google
- World Nuclear News — “Regulator extends Hermes 1 reactor construction deadline,” April 22, 2026.
- U.S. Nuclear Regulatory Commission — Hermes construction permit docket. https://www.nrc.gov/reactors/non-power/new-facility-licensing/hermes-kairos
- S&P Global — “Google partners with advanced nuclear developer on three sites totaling 1.8 GW,” May 8, 2025.
- Talen Energy — SEC Form 8-K, June 11, 2025. Amazon PPA announcement. https://www.sec.gov/Archives/edgar/data/0001622536/000162828025030559/a20250611pressreleasebusin.htm
- Talen Energy — Investor relations press release, “Talen Energy Expands Nuclear Energy Relationship with Amazon,” June 11, 2025. https://ir.talenenergy.com/news-releases/news-release-details/talen-energy-expands-nuclear-energy-relationship-amazon
- Amazon — “Amazon signs agreements for innovative nuclear energy,” October 2024. https://www.aboutamazon.com/news/sustainability/amazon-nuclear-small-modular-reactor-net-carbon-zero
- Pew Research Center — Nuclear energy public opinion survey topline, April–May 2025. https://www.pewresearch.org/short-reads/2025/10/16/support-for-expanding-nuclear-power-is-up-in-both-parties-since-2020/
- Bisconti Research — 2025 National Nuclear Energy Public Opinion Survey. https://www.bisconti.com/blog/public-opinion-2025
- Gallup — “Nuclear Energy Support Near Record High in U.S.,” 2025. https://news.gallup.com/poll/659180/nuclear-energy-support-near-record-high.aspx
- RISE Research Institutes of Sweden — GPT-4 training energy analysis. https://www.ri.se/en/news/blog/generative-ai-does-not-run-on-thin-air
- Tom’s Hardware — “Meta turns to nuclear power for AI training,” 2025. https://www.tomshardware.com/tech-industry/artificial-intelligence/meta-turns-to-nuclear-power-for-ai-training-asking-for-developer-proposals-for-small-modular-reactors-or-larger-nuclear-solutions
- Data Center Dynamics — Oracle SMR data center announcement, September 2024. https://www.datacenterdynamics.com/en/news/oracle-to-build-nuclear-smr-powered-gigawatt-data-center/
- U.S. Department of Energy — Kairos Power Hermes molten salt testing project. https://www.energy.gov/ne/articles/kairos-power-wraps-molten-salt-testing-project
- Reuters (via Utility Dive, Vision Times, ecmsource.com) — ERCOT “ghost demand” and Texas grid connection freeze, September 1, 2026.
- Wood Mackenzie analysis of PJM large-load growth (55 GW by 2030), as reported in White & Case, “PJM proposes to carve out new services for co-located data centers,” March 2026; underlying PJM FERC filing, May 2026. https://www.pjm.com/-/media/DotCom/documents/ferc/filings/2026/20260507-el26-63-000.pdf
- CISA — Energy sector cybersecurity advisories. https://www.cisa.gov/topics/critical-infrastructure-security-and-resilience/critical-infrastructure-sectors/energy-sector