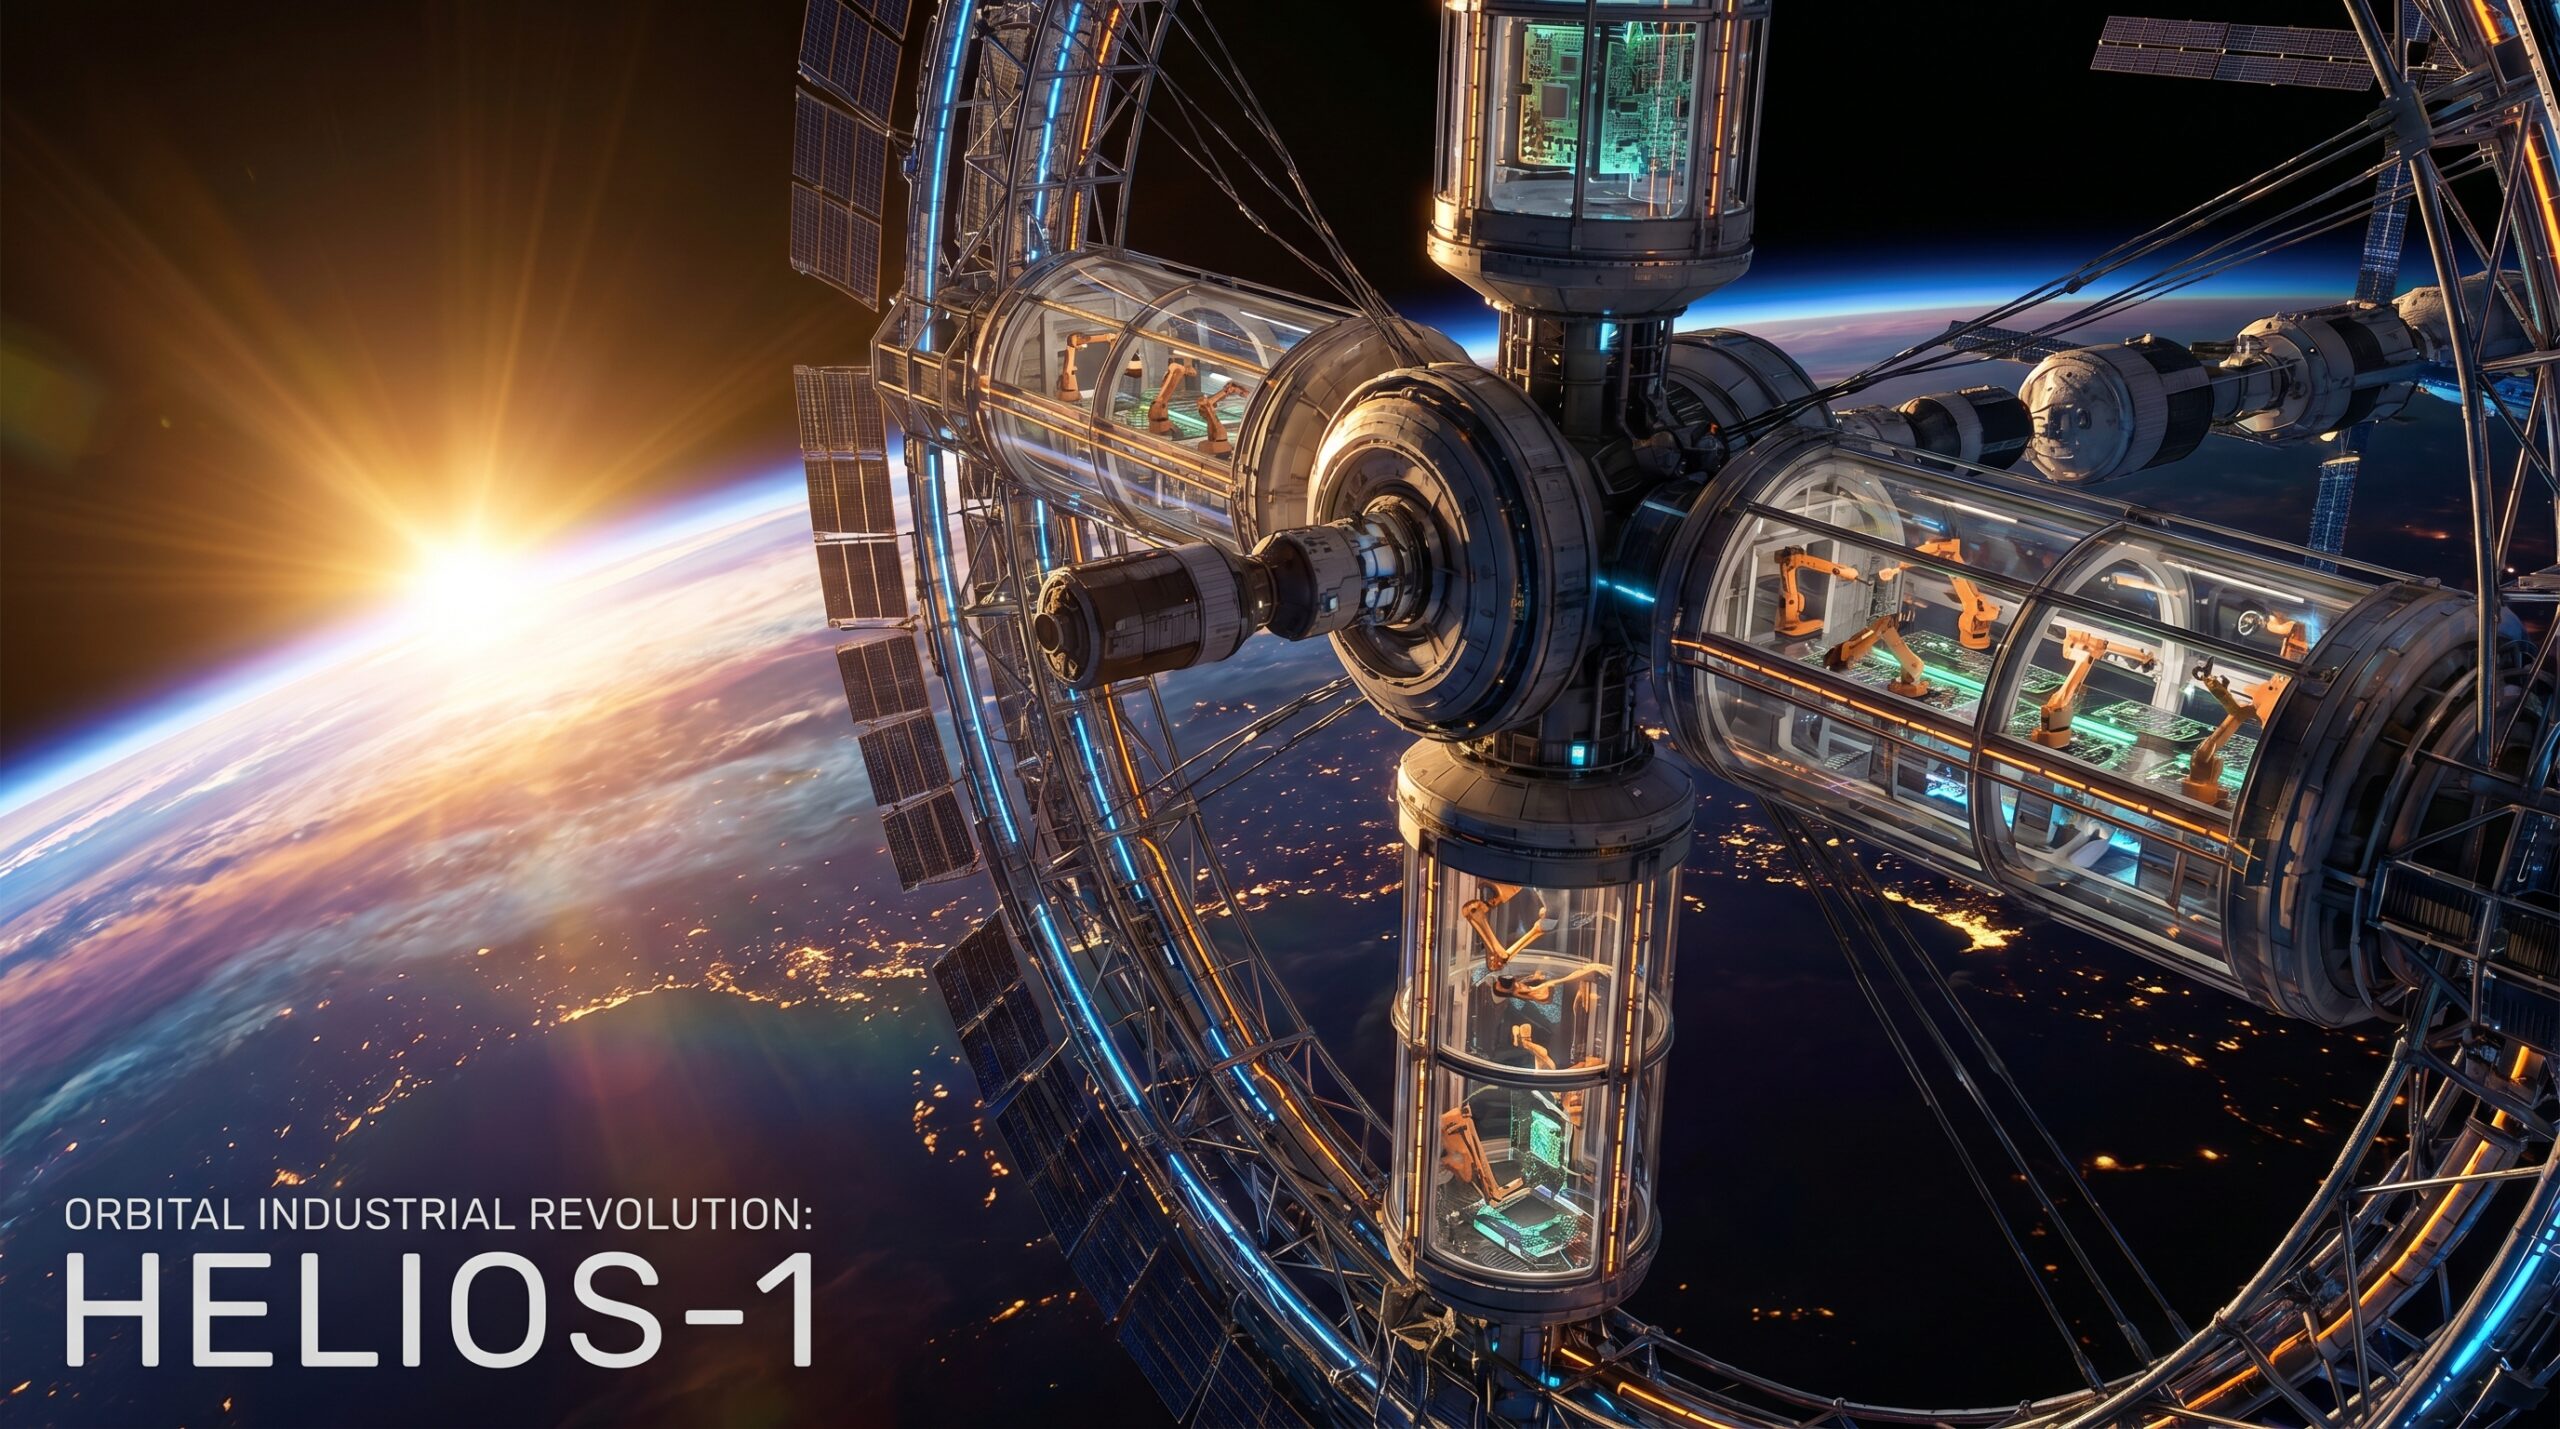
Why the Next Industrial Revolution Could Start 250 Miles Above Earth
A deep dive into the future of orbital factories, space manufacturing, AI automation, and the trillion-dollar space economy.
Table of Contents
Okay, start here: a drug. Cooked in space. Landed in the Utah desert. And the crystals survived the trip.
I know how that sounds. I thought the same thing. But that’s not a press release — that’s the finding of a ChemRxiv preprint from Varda Space Industries and Improved Pharma LLC, and it’s the clearest sign I’ve seen that something real is happening 250 miles up. (Technically 370–460 km, since the ISS drifts as atmospheric drag pulls it down between reboosts — but “250 miles” is close enough for the conversation we’re about to have.)
The International Space Station is already making drugs, printing human tissue, and growing specialty semiconductor structures for researchers on the ground. Today. Not in ten years. Today. I’ve been watching this space for a while, and I think most people — including a lot of people in industry — are sleeping on what that actually means.
So let’s get into it.
Forget What You Think You Know About Space
Most people hear “space manufacturing” and picture astronauts with wrenches. That’s not this.
I think the better mental model is: what if gravity was a bug in your process? Because for certain products — pharmaceutical crystals, fiber optic preforms, biological tissue — it genuinely is. Gravity causes three things that wreck manufacturing quality:
- Sedimentation — heavy bits sink during liquid processing and seed impurities through your whole batch
- Convective currents — heat differences push fluid around and trash the crystal lattice you were trying to grow
- Buoyancy effects — light materials float up during solidification and create weak spots throughout the end product
Kill gravity, and all three largely go away. Per a May 2025 in-space manufacturing analysis by Robotics & Automation News, microgravity produces materials with fewer defects and greater structural uniformity — including ultra-pure fiber optics with signal loss profiles you simply can’t hit on the ground.
One caveat worth being precise about, because it matters for exactly the processes we’re talking about: “microgravity” doesn’t mean zero acceleration. Per NASA’s own accelerometer data from the ISS — the MAMS and SAMS systems, which have been operating nearly continuously since 2001 — the station’s quasi-steady acceleration runs on the order of a few micro-g during dedicated microgravity operations. But the vibratory environment is messier and depends heavily on frequency, location, and what equipment happens to be running. Per NASA’s own ISS Researcher’s Guide to the acceleration environment, the station’s overall spectrum — without additional isolation — ranges from well under a micro-g at the lowest frequencies up to well over 10 milli-g at the higher end, with individual disturbance sources (exercise equipment, fans, pumps, antenna gimbals, attitude-control activity, structural flexing) each contributing their own signature in between. Crew exercise, thruster firings, structural flexing, even someone pushing off a wall — all of it shows up as residual acceleration at the experiment site.
For crystal growth and other fluid-sensitive processes, that residual jitter isn’t a footnote. It’s the gap between the theoretically perfect microgravity environment you’d design a process around and the actual, messier one you get. Process tolerance has to account for the real vibratory spectrum, not an idealized zero-g assumption — which is part of why some ISS payloads use dedicated vibration isolation racks (NASA’s own data shows these racks measurably cut vibration at the isolated location compared to a hard-mounted one). It’s also a reasonable engineering inference — not a documented measurement of Varda’s capsule specifically — that a free-flying, uncrewed platform with no structural connection to a much larger, mechanically busy station would face fewer of those disturbance sources in the first place. Fewer potential noise sources doesn’t guarantee a quieter environment, but it’s the same logic the ISS’s own isolation systems are built on: distance and disconnection from the disturbance source helps.
Now — and I want to get this right, because most coverage gets it wrong — vacuum is not the same as clean. I’ve noticed that a lot of “space = no contamination” takes skip past the actual engineering. In vacuum, materials off-gas: they release trapped gases and volatile organic compounds (VOCs) that drift and condense as thin films on every surface they find, including your sensitive hardware. NASA has qualification standards for exactly this — materials destined for flight are screened and, where warranted, put through thermal-vacuum bake-out under NASA outgassing standards before they fly. The contamination problem doesn’t go away. It changes shape.
Heat is brutal too. No air means no convection, which means heat from any manufacturing process can only leave by conduction or radiation. You need purpose-built radiators. You need to budget your power density carefully — and this constraint gets more acute as you add autonomous compute to the platform. (The broader AI energy problem that makes this hard is something I covered here.) And every 90-minute orbit includes roughly 45 minutes of sunlight and 45 minutes of darkness — thermal swings, over and over, stressing everything, including the energy storage systems that keep the platform running through eclipse. Solid-state batteries are one technology being watched closely for exactly this application — higher energy density, no liquid electrolyte to off-gas or leak in vacuum. Loose particles just float. Forever. Which is why cutting and grinding — subtractive manufacturing — is essentially off the table in orbit without specialized containment.
Then there’s radiation, and I think this is the one that gets undersold the most. Low Earth Orbit hits every piece of hardware with galactic cosmic rays, solar particle events, and trapped protons from the Van Allen belts. These cause single-event upsets (SEUs) — bit-flips in memory and logic that can crash a system mid-process. Plus cumulative total ionizing dose (TID) that degrades electronics slowly over the mission. The ISS crosses the South Atlantic Anomaly — a zone of elevated trapped-particle flux — on every orbit. Per peer-reviewed work in MDPI Electronics (2023), shielding helps against lower-energy particles, but at the energies galactic cosmic rays carry, added shielding mass has sharply diminishing returns — those particles carry enough energy to punch through any practical mass of material. You design around it instead: error-correcting code (ECC) memory, radiation-hardened compute, fault-tolerant architectures, redundancy baked in everywhere. (I covered how satellite PCB engineers solve exactly these radiation constraints in depth — if you want the board-level detail, that piece is here.)
On the other hand — and maybe I’m wrong about the framing here — all of these constraints are known. Solved or solvable. Per the March 2025 review in MDPI Manufacturing, they’re well-documented challenges, not unknowns. The reason orbital manufacturing is compelling isn’t that it avoids hard problems. It’s that for specific high-value product types, the upside of removing gravity structurally outweighs the cost of managing everything else. That’s the whole argument. Not space for everything. Space for certain things.
So What Does It Actually Look Like Right Now?
Start with the drug. Because this is the one that made me stop and re-read it twice.
Varda Space Industries — a startup I’d vaguely tracked — launched a compact, unmanned capsule to low Earth orbit (LEO) on a SpaceX Falcon 9 in June 2023. The capsule was a pharmaceutical manufacturing unit. The target: ritonavir, an antiretroviral HIV drug.
Seven months later the thing came screaming back through the atmosphere at hypersonic speeds over 18,000 miles per hour and landed in Utah on February 21, 2024.
Here’s what came back. Per the ChemRxiv preprint from Varda and Improved Pharma LLC — not yet peer-reviewed, worth being clear about that — the mission crystallized ritonavir into Form III, a polymorph independently characterized in peer-reviewed work (published in Crystal Growth & Design) as having promising bioavailability properties compared to other ritonavir forms, and one that’s difficult to nucleate consistently — it only forms in a narrow temperature window with a slow nucleation rate. The orbital study’s specific finding was about crystal stability through processing and reentry, not a head-to-head bioavailability comparison against Earth-made material. Microgravity suppresses the convective currents and sedimentation that disrupt crystal lattice formation on the ground, and the supplementary data compares crystallinity between Earth-grown and space-grown samples.
The crystals survived reentry. Form held.
I know what you’re thinking — one drug, one mission, not a factory. Fair. But according to Varda’s own platform documentation, microgravity processing has the potential to improve shelf-life, bioavailability, and formulation consistency across small molecule drugs and biologics — outcomes in active early-stage research, not yet validated in clinical trials. And compelling enough to raise $329 million in funding, including a $187M Series C in July 2025 led by Natural Capital and Shrug Capital. Think about every drug that requires cold-chain shipping because it falls apart at room temp. Think about monoclonal antibodies that won’t crystallize uniformly in a ground facility. Space might be the only place some of these processes work at all.
Who Else Is Building Up There?
Redwire Space
Varda gets the headlines, but Redwire is arguably doing more actual work on the ISS right now than any other commercial outfit. Per their own June 2024 press release (NYSE: RDW), they had ten active payload facilities on the station at that time — more than any other commercial entity. By December 2025 that grew to eleven, per the full-year 2025 earnings report. The count shifts as experiments cycle through resupply missions, but it’s been going one direction.
I think the history here matters and gets glossed over. The Additive Manufacturing Facility (AMF) — Redwire’s flagship platform, the first permanent commercial manufacturing system in LEO — wasn’t built by Redwire. It was built by Made In Space, which launched it in 2016. Redwire acquired Made In Space in 2020. Per the ISS National Lab database, the AMF has produced over 200 tools and components on-orbit, printing in ABS, PEI-PC, and HDPE. Good platform. Solid track record.
But honestly? The bioprinting work is the part that keeps pulling me back.
Redwire runs a separate platform — the 3D BioFabrication Facility (BFF), originally built by Techshot Inc. before Redwire acquired them — and in July 2023 they used it to bioprint the first human knee meniscus in orbit, as part of the BFF-Meniscus-2 investigation. Live human cells. Cultured for two weeks in the Advanced Space Experiment Processor (ADSEP). Returned to Earth in September 2023 on Crew-6.
Then in April 2024, the same BFF platform bioprinted live human heart tissue in orbit. Without scaffolding. Per Redwire’s official May 8, 2024 press release via Business Wire (NYSE: RDW): no scaffolding needed, because in microgravity the soft tissue holds its own three-dimensional shape — it doesn’t collapse under gravity the way it does on Earth, where you need chemical thickeners or physical scaffolds just to keep the structure intact during the print. (That last detail is the one I keep telling people about. It sounds fake. It’s not.)
The implications for regenerative medicine aren’t coming — they’re being tested right now in pre-clinical research settings. Which is where they need to be before anyone makes a clinical claim. If you want to see where the biology-meets-hardware story goes next, this piece on biocomputing and living cells connects directly.
The NASA ODME Program
Here’s one that doesn’t get enough attention. NASA’s On Demand Manufacturing of Electronics (ODME) program is building a high-precision inkjet printer capable of making ReRAM (Resistive Random-Access Memory) chips in microgravity. The team includes Intel, Axiom Space, TEL (Tokyo Electron Limited), Arizona State University, and the University of Wisconsin — per Factories in Space’s orbital microfabrication documentation.
I want to be clear about scope, because this gets hyped wrong constantly. This is not a challenge to TSMC. At all. Modern high-volume chip production runs on extreme ultraviolet (EUV) lithography, sub-3nm overlay precision, and process control at atomic scales — gravity is not the limiting factor there. What orbital manufacturing targets is a completely different tier: exotic crystal substrates, radiation-hardened niche parts, low-volume specialty components that are genuinely hard to grow uniformly under gravity. The ODME approach uses electrohydrodynamic (EHD) printing — non-contact, direct-deposit, no photomasks — for exactly that low-volume, high-value use case. Parabolic flight testing was completed, with ISS deployment originally targeted for the 2024–2025 window; per NASA’s TechPort project record, the program has continued past that original window rather than concluding on schedule.
Sierra Space and Astral Materials
In December 2024, Sierra Space signed memoranda of understanding with Astral Materials and Space Forge for microgravity semiconductor development on the upcoming Dream Chaser vehicle. Astral Materials put it plainly: “Our technology uses microgravity as a manufacturing tool that can only be accessed in space.” Hard to argue with that framing.
The Money Part
At the end of the day, none of this matters if the numbers don’t work. So let’s do the numbers.
Launch costs have dropped tenfold over the past two decades, per SpaceNews analysis from April 2024 — driven mainly by SpaceX’s reuse model. Annual satellite deployment has been growing at roughly 50% year-over-year. But — and this is the part people forget — $/kg to orbit isn’t the whole cost. Insurance, payload qualification, integration, reentry certification, orbital debris mitigation: all real overhead, all modeled separately by serious aerospace investors. The full cost stack needs to compress, not just the launch price.
That said, when your product sells for hundreds of thousands of dollars per kilogram — pharmaceutical crystals, ZBLAN fluoride fiber optic preforms, specialty semiconductor substrates — the math starts working in ways that don’t apply to a communications satellite.
The big-picture projections: Morgan Stanley Research sees the global space industry growing to over $1.1 trillion by 2040. Goldman Sachs has independently put it at roughly $1 trillion by the same date. Bank of America Merrill Lynch equity research goes to $2.7 trillion by 2045. Those figures span the whole space economy — launch, comms, remote sensing. In-space manufacturing is the piece where you’re actually making physical stuff. That wedge is still wide open.
The Factory Can’t Have a Human Boss On-Site
Here’s a thing I’ve noticed that doesn’t come up enough: you physically cannot staff these factories with people.
The ISS was designed for a crew of seven — that’s not the binding constraint though. The binding constraint is the ECLSS (Environmental Control and Life Support System) capacity, and the fraction of that crew’s time that’s actually free for commercial manufacturing work is tiny. Future commercial stations face the same wall. At scale, these facilities have to run on their own.
That means the full stack:
- Machine vision for in-process quality checks
- Autonomous robotic arms for handling and assembly
- Autonomous control systems running pre-programmed process sequences
- Remote monitoring with near-zero human intervention
None of that hardware is exempt from the thermal cycling problem covered earlier — and this is where automation actually raises the stakes rather than lowering them. Every time the platform crosses from sunlight into eclipse and back, the electronics running that machine vision system, that robotic arm, that control loop, go through a temperature swing. Different materials in an electronic assembly — the board laminate, the component package, the solder joint holding them together — expand and contract at different rates as temperature changes. That mismatch concentrates mechanical stress right at the solder interconnect, and over enough cycles, it can fatigue the joint toward an intermittent or fully open connection. This is a well-characterized failure mode in terrestrial electronics, too — IPC-9701 specifically standardizes accelerated thermal cycling tests for exactly this kind of solder-attachment fatigue. Connectors face a related but distinct version of the same underlying problem: repeated thermal cycling and mechanical stress can degrade contact integrity over time, separate from the solder-joint mechanism, but with a similar practical result. In orbit, though, there’s no technician to reseat a connector or reflow a joint. An intermittent connection in a sensor or actuator can look like a process fault long before anyone diagnoses it as a hardware fault. The practical response is redundancy — parallel sensors, backup actuation paths, components chosen for better CTE compatibility with the board — but redundancy costs mass and power on a platform where both are already tightly budgeted. Autonomy doesn’t remove this problem. It just shifts the burden from “a person walks over and checks it” to “the system has to know something is wrong without being told.”
That’s the real engineering question sitting underneath “the factory needs no human boss”: if a process fails halfway through a high-value run — a sensor drops out, an actuator sticks, a control loop faults — can the system figure out what broke and recover, or does the whole batch get scrapped? NASA and ESA have a term for this: FDIR, fault detection, isolation, and recovery, and it’s been a long-established engineering practice on uncrewed spacecraft for decades, precisely because ground control can’t always intervene in real time. In practice that means health telemetry granular enough to localize a fault, logic that can isolate the failed component without shutting down the whole process, some form of redundant path or safe-state behavior to fall back on, and either an autonomous restart routine or a way to preserve process state until ground control can weigh in. None of that is exotic engineering — it’s the same reasoning that’s kept robotic spacecraft operating for years without anyone on board. But it’s a meaningfully different problem than “remote monitoring,” which just tells you something is wrong. FDIR can determine whether that failure costs you one sensor reading or the entire manufacturing run — and the more valuable what’s inside that batch is, the more that distinction is worth getting right.
Current platforms — Redwire’s AMF and BFF, Varda’s capsule — run deterministic, pre-programmed autonomous sequences. That’s not ML. Worth being precise. But Redwire is actively closing the gap: in May 2024 they became a founding corporate sponsor of the Center for AEroSpace Autonomy Research (CAESAR) at Stanford, investing in machine learning, computer vision, and autonomous reasoning for space vehicles. Their MSTIC semiconductor platform — which completed a pathfinder mission on the ISS in 2024 — is already described by Redwire as “an autonomous semiconductor manufacturing platform.” CTO Al Tadros in the CAESAR announcement: “AI-enhanced capabilities could be transformative for in-space servicing, GNC and RPO autonomy, and a range of complex mission requirements.”
I’ve found that the companies with the most credible orbital manufacturing progress are also the ones deepest in terrestrial automation work. Space just forces the timeline. The hardware gaps in autonomous factory systems — on Earth or in orbit — are worth understanding: I broke them down here.
A Bit of History (Bear With Me)
Every big industrial shift needed two things: a new physical environment that changed what was possible, and a drop in the cost to get there.
Coal made the first one go. Electricity the second. Silicon and software the third.
I think — and maybe I’m putting too clean a bow on this — the fourth one is microgravity and vacuum as manufacturing conditions, made reachable by falling launch costs, run by systems that don’t need a person on site. The output isn’t raw ore. It’s finished goods: purer drugs, lower-loss fiber, novel crystal structures, tissue you can grow without a scaffold.
Earth’s gravity isn’t just physics. For certain processes, it’s a bug. We’ve been working around it for centuries because we had no choice.
What to Watch — Practically Speaking
Don’t sweat the big picture for now. Here’s the specific stuff worth tracking:
Reentry economics. Varda’s model — capsule up, product made, capsule down — is the near-term playbook. The ratio that matters: payload value per kg versus full-stack mission cost per kg. When that math works, this industry moves fast.
ZBLAN fiber. Made In Space (now Redwire) has been developing ZBLAN fluoride fiber optic cable for years, and the underlying physics case is real — ZBLAN’s theoretical attenuation limit is two to three orders of magnitude below silica fiber, and gravity-driven microcrystallization is a documented reason terrestrial manufacturing has never hit that limit. But be careful with how settled this is commercially: independent, published attenuation comparisons between space-drawn and Earth-drawn ZBLAN have been “the next major inflection point” for this industry for several years running, and as recently as early 2026 comprehensive third-party comparisons were still described as pending. A peer-reviewed multi-organization study published in Space: Science & Technology in mid-2026 does report lower attenuation and better mechanical performance from space-drawn fiber — a real and recent data point — but “dramatically lower attenuation, commercially proven” is not yet where the field has landed. Worth watching, not yet worth assuming.
The drug pipeline. Varda is publicly moving from small molecules into biologics — monoclonal antibody crystallization specifically. Multi-billion-dollar segment. Real unsolved formulation problems. Worth watching closely.
Station handover. The ISS is scheduled for decommission around 2030. NASA’s Commercial Low Earth Orbit Destinations (CLD) program is funding successors now. Whoever builds those stations owns the factory floor. That’s not a figure of speech.
The Honest Part
I want to be real here: the gap between “we proved it works” and “this is a scalable industry” is enormous. And I’d be doing you a disservice to skip past that.
Costs need to fall more. Return logistics need to become boring routine. The products that benefit most from microgravity are — almost by design — the hardest ones to make, which means the debugging phase takes years, not quarters.
The regulatory piece is the one I think about most. Here’s the case study: Varda’s W-1 capsule finished its ritonavir crystallization within weeks of the June 2023 launch. Done. But the capsule couldn’t come home — the FAA hadn’t issued a reentry license under the legacy Part 431 framework. It sat in orbit six more months, burning power and operational life, waiting. Per TechCrunch’s November 2025 interview with Varda CEO Will Bruey, compressing that latency is still a top priority.
On the other hand — maybe I’m too focused on the bottlenecks — the regulatory framework has actually been getting better for a while now, even if it doesn’t always feel that way from inside a specific delay. The FAA’s consolidated Part 450 framework — one performance-based rule replacing the four legacy parts (415, 417, 431, and 435) — has technically been in effect since March 2021. What changed on March 10, 2026 is that the transition period ended: those four legacy parts were formally removed from the Code of Federal Regulations, and Part 450 became the only game in town. Varda’s W-1 mission, back in 2023, could still use the older Part 431 track during that transition window, which is part of why the case study above is dated the way it is. And the broader trend is real regardless of exactly which framework a given mission used: per the FAA’s own data, FY2025 saw 199 licensed commercial launches and reentries. In 2015, that number was nine. Nine. That’s not incremental progress. That’s a structural change.
The physics isn’t going anywhere. Gravity will still break crystal lattice formation tomorrow exactly the way it does today.
The only question is how fast everything else catches up.
Based on what landed in a Utah desert in February 2024 — I think the answer is: faster than the industry is ready for.
About the Author
Imran Valiani | Sales Director, PCB Electronics Manufacturing
20+ years working with major Bay Area and global tech clients. Founder of Silicon to Software, where I write about the hardware layer — PCB fab, AI gear, autonomous systems, and cyber — the stuff most tech writers have never touched. Literally.
Follow: X @SiToSoftware | LinkedIn
For more analysis of radiation, reliability, electronics, and manufacturing constraints beyond Earth, explore the Space Electronics & Aerospace Resource Hub.
This article was developed with AI assistance and edited, fact-checked, and reviewed by the author. See my full AI disclosure.
Sources
- NASA ISS Reference Page — nasa.gov/reference/international-space-station
- Kennedy Space Center FAQ — kennedyspacecenter.com
- Robotics & Automation News — in-space manufacturing analysis, May 2025
- ISS National Lab — AMF and BFF facility pages
- Redwire Corporation — press releases, June 5, 2024 and May 8, 2024 (NYSE: RDW)
- Redwire Corporation — Q4/Full Year 2025 Earnings Report, February 2026
- 3D Printing Industry — Made In Space acquisition report
- 3DPrint.com — Ken Savin interview, October 2024
- Varda Space Industries / Improved Pharma LLC — ChemRxiv preprint, 2024
- Parent et al. — Crystal Growth & Design, 2023 (ACS Publications)
- Varda Space Industries — Series C announcement, PRNewswire, July 10, 2025
- TechCrunch — Will Bruey interview, November 2025
- MDPI Manufacturing — in-space manufacturing review, March 2025
- MDPI Electronics — SEU analysis, 2023
- NASA ISS Researcher’s Guide: Acceleration Environment (NASA JSC/GRC)
- NASA NEPP — lead-free soldering report
- IPC-9701 — thermal cycling test standard
- NASA Technical Reports Server — FDIR documentation
- NASA TechPort — ODME Program, Project
#155248 - Factories in Space — factoriesinspace.com
- Astral Materials — official company statement
- Morgan Stanley Research — “Investment Implications of the Final Frontier”
- Goldman Sachs / U.S. Chamber of Commerce — space economy report
- Bank of America Merrill Lynch — equity research
- SpaceNews — “The Trillion-Dollar Question,” April 19, 2024
- FAA — Federal Register, faa.gov; Vehicle Operator License documentation
- Congressional Research Service — Report R48582
- Aerotecnica Missili & Spazio (Springer Nature) — ZBLAN fiber research
- New Space Economy — ZBLAN industry analysis, February 2026
- Space: Science & Technology — ZBLAN comparative study, 2026